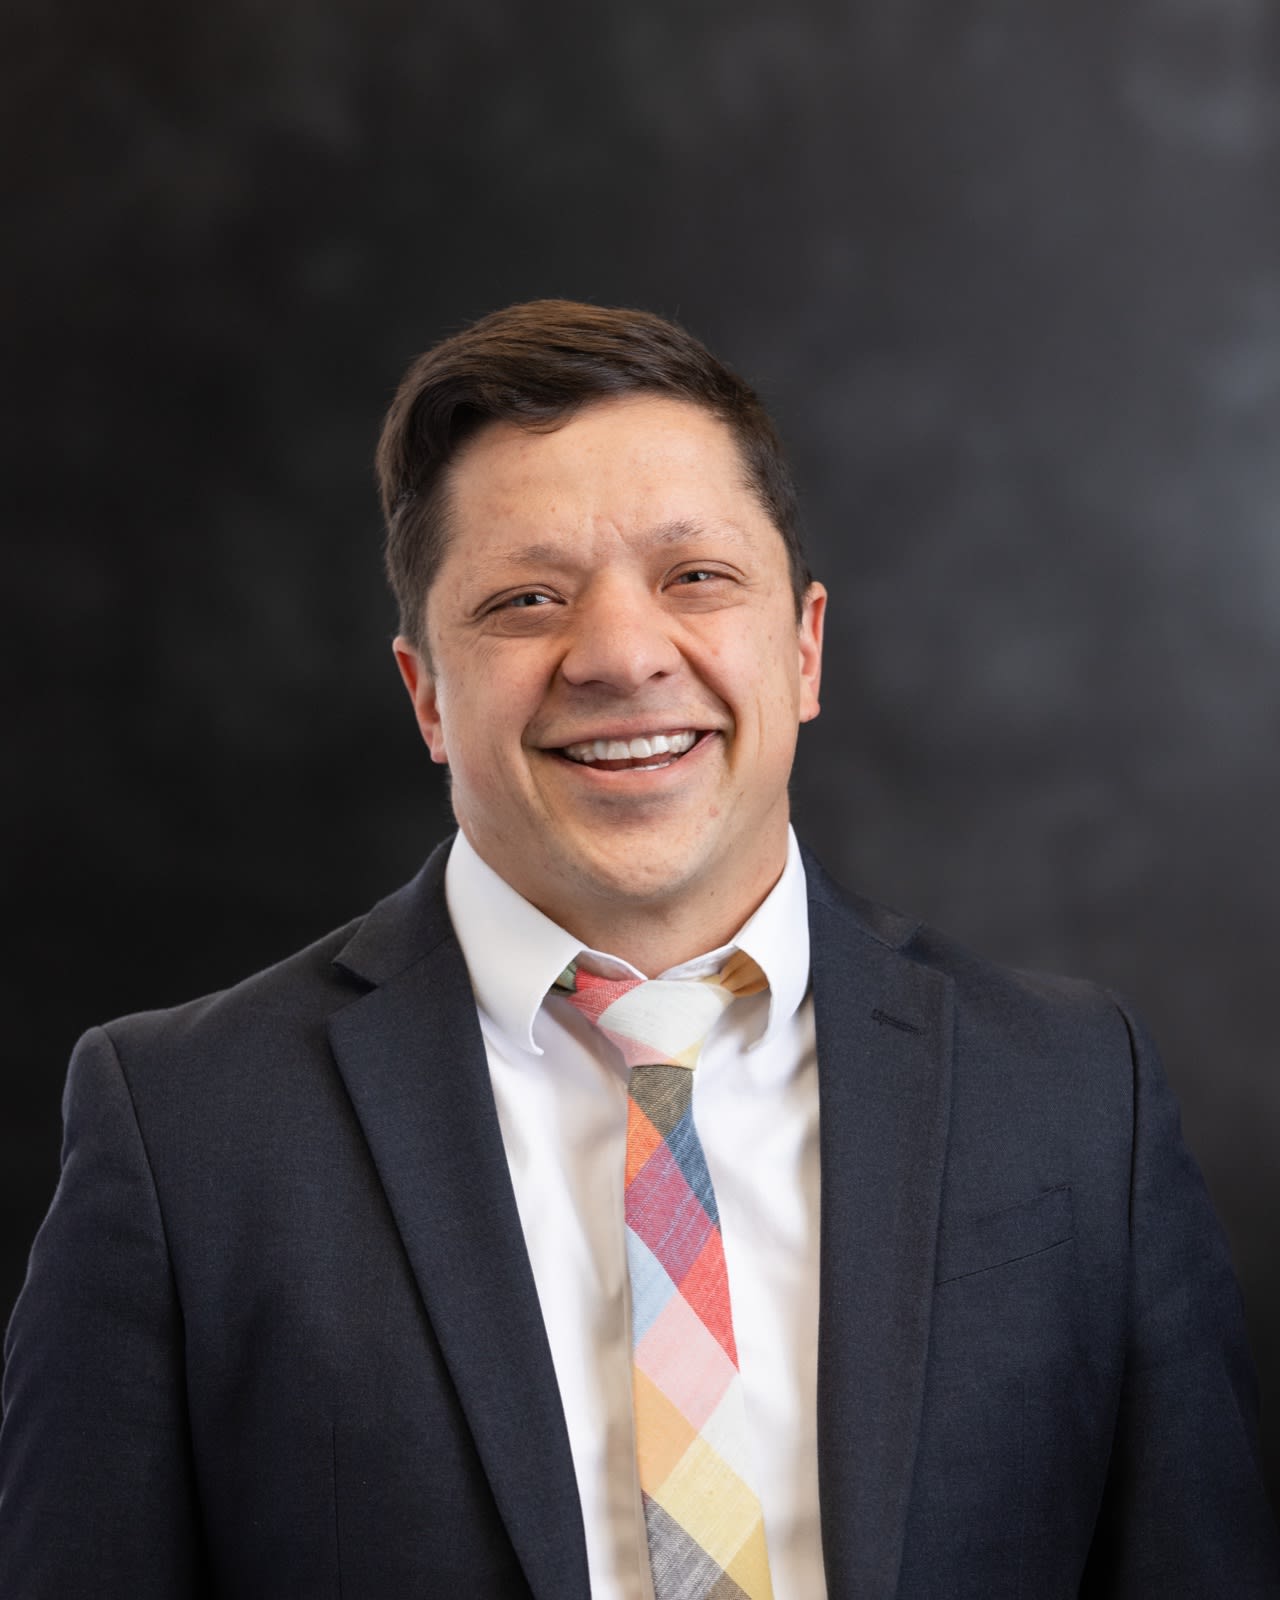
I'm James Briggs.
I help individuals, families, and business owners with life and health insurance, Medicare, and retirement planning. Budgets and goals vary a lot, and that’s fine. Everybody deserves to feel financially secure — whether they’re protecting a young family or figuring out how to turn savings into income they won’t outlive.
Most people I meet aren’t careless about their money. They’ve just never had someone explain the options plainly, without steering them toward a product in the first ten minutes. Jargon is how people end up buying something they don’t understand — or, more often, putting the whole thing off for another year.
My process starts with your goals, not a product. We’ll look at where you are, review any coverage you already have, and work through the questions you’ve been carrying around. Some conversations end with a policy. Some end with you knowing you’re already in good shape. Either way, you’ll understand the tradeoffs well enough to decide for yourself.
Why Harbinger, and why HBG
HBG is Harbinger. The practice is Harbinger Wealth; HBG is just the short form, the way it fits on a business card and a sign.
A harbinger is someone who goes on ahead and tells you what's coming — and that's the whole idea. Almost nothing that goes wrong in retirement planning goes wrong because someone picked the wrong product. It goes wrong because a window opened and closed while nobody was watching it.
Turning 65 without knowing that your enrollment window started three months before your birthday. Retiring at 62 and discovering what health coverage costs between then and Medicare. Taking Social Security the year you become eligible because nobody showed you what waiting would have been worth. Each of those is a decision with a date on it, and the date arrives whether or not anyone has thought about it.
So the job, as I understand it, is to be a little way ahead of you on the road: here's what's coming, here's when it matters, and here's what you'll want to have decided by then.
Sometimes that means putting something in place. Very often it means telling you there's nothing to do yet, and when to look again.
The compass on this site is the same idea drawn: four things worth keeping an eye on — healthcare, legacy, assets, and income — and a needle that tells you which one you're heading toward next.
Early beats optimal
A good decision made in time beats a perfect one made late. Most of what I do is move the conversation earlier.
Say the date out loud
Every recommendation comes with when it matters and what happens if it slips. A deadline you can see is one you can plan around.
"Nothing yet" is an answer
If there's nothing worth changing, I'll say so and tell you when to check again. That's the version of this job worth having.

However it works best for you.
I meet clients in person, over video on Zoom, or on the phone. There's no right answer — we'll work out together which is most helpful for you, and that can change from one conversation to the next.
How I work
A conversation first
The first call is about your situation, not a plan. If there's nothing to do yet, I'll tell you that and when to check back.
Plain language
I'll explain how something works before I explain what it costs. If I use a term you haven't heard, stop me — that one's on me, not you.
No pressure, ever
You will never get a "this offer ends today" from me. Real deadlines come from Medicare and from your birthday, and I'll tell you exactly what they are.
Experience that carries over
Before insurance, I spent fifteen years in product work. The job was sitting with people, figuring out what they actually needed rather than only what they first asked for, and cutting through the noise to get there. It’s the same skill this work requires, pointed at a different problem.
I earned my MBA from the University of Utah and hold life and health insurance licenses. I’m studying for the Series 65 because I’d rather understand a person’s whole financial picture than one slice of it.
My wife and I also run a small business together. Payroll, taxes, benefits, and income that doesn’t arrive on the same day every month are not abstractions to me. If you’re a business owner, we’ll speak the same language.
I chose to be independent so the conversation can start with your situation, not a carrier’s sales target. I live in Utah with my family and like being someone my neighbors can call with a question — even when the answer is that they don’t need to buy anything today.
Credentials and coverage area
Licensed in
Utah & Idaho
Resident Utah agent
National Producer Number
21441122
Education
MBA
Primary service area
Wasatch Front
Statewide Utah and Idaho, in person or by video
Independent
Not captive
Not employed by any insurance company